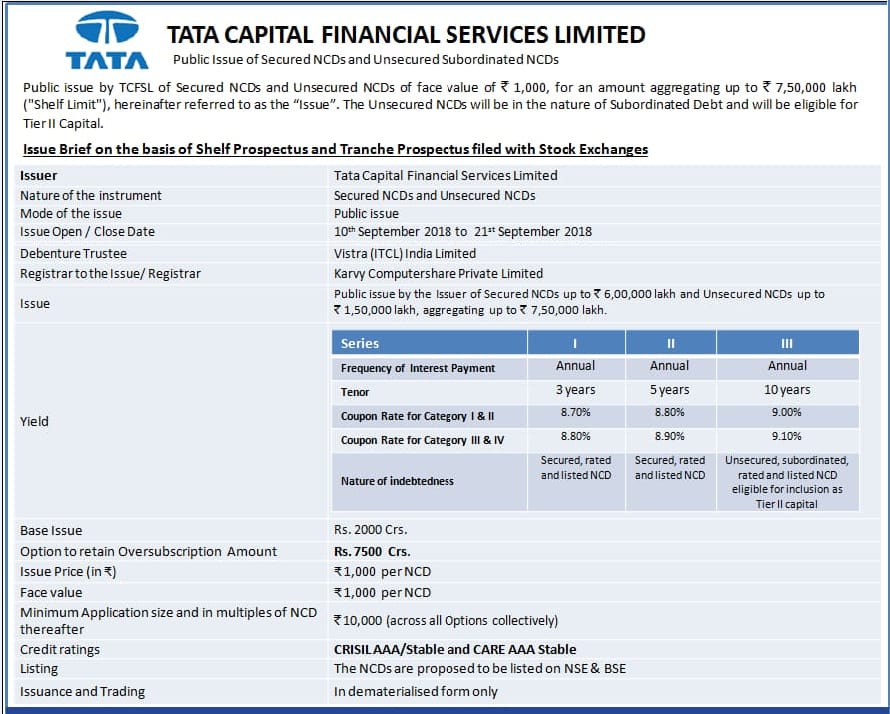
NCD Public issue of *Tata Capital Financial Services Limited * Issue Size: *₹ 7,500 Crores* Instrument: *Secured Redeemable Non-Convertible Debentures and Unsecured, Subordinated, Redeemable, Non-Convertible Credit Rating: "CRISIL AAA / Stable" by CRISIL; and "CARE AAA; Stable by CARE* Listing:*Proposed to be listed on BSE & NSE* Issuance Mode: *Demat* Face Value: *₹ 1000* Mode Of Application: *ASBA/Non ASBA* Issue Opening Date: *10th September 2018*
Bond yields still down; keep tight range
Benchmark 10-year bond yield lower 2 basis points at 8.78 per cent having traded in a tight 8.77-8.79 per cent band during the session.
Bond investors awaiting fiscal 2014/15 first-half borrowing calendar with finance ministry and RBI officials due to meet on Friday.
India intends to borrow Rs 5.97 lakh crore in next fiscal, with dealers expecting around 60 per cent to be routed in the first half.
"Yields should not be impacted materially. One should need at tenor buckets," says a senior dealer. Most market participants still expect the central bank to hold rates at its April 1 policy review.
Thanking you
Regards,
Rajesh Kumar Kathpalia ¤ SMC Global
17,Netaji Subhash Marg,Daryaganj,
New Delhi-110002 Mobile No 9891645052
Email Id: rajesh.ipo@smcindiaonline.com
--
You received this message because you are subscribed to the Google Groups "Product Updates for AMC" group.
To unsubscribe from ...
👉Rules Applicable for NRI Income tax will be deducted at source under Section 195 of the Income Tax Act, 1961, at the rates in force. Wherever there exists a Double Taxation Avoidance Agreement (DTAA) between Government of India and Government of other Countries (country of Residence of respective NRI), the rate of tax deducted at source will be applied as per the DTAA. NRI has to give the declaration each financial year in two respects, viz.,that he is a resident of foreign country and he is not resident in India, during the relevant Financial Year, failing which TDS will be deducted at normal rates. To claim benefit of DTAA, it is compulsory to submit Tax Residency Certificate and Form 10F. Where income tax is deducted at source on the monthly interest a consolidated TDS certificate may be issued for the financial year. Sub-section 5A of Section 139A of the Income Tax Act, 1961 requires every person receiving any sum or income from which tax has been deducted to inti...
 Tata Mutual Fund has launched a closed-ended equity fund, Tata Value Fund Series-1.


Comments
Post a Comment
You are requested to mentioned your full name with email id while commenting.